 +44 20 3885 6670
 瑞士Financial ServicesL#20261222
Established Swiss VASP & Fintech Platform
An turnkey opportunity to acquire a full…
- 目标价格
- 价格面议
- 营收
- 待定
- EBITDA
- 待公布
 加拿大
A Canadian merchant services business with this profile is highly viable and marketable, though its appeal concentrates in specific buyer tiers rather than broad-market institutional private equity.
Key Strengths Supporting Viability:
A 58% adjusted EBITDA margin on net revenue reflects a lean, asset-light operating model with low fixed overhead and minimal capex.
98% recurring revenue reduces cash flow volatility, making post-acquisition integration or debt service straightforward.
Partnering across multiple processors mitigates single-counterparty de-platforming risk, a common deal-breaker for small ISOs (Independent Sales Organizations).
Zero existing debt simplifies transaction mechanics and enables accretive financial engineering for buyers utilizing senior leverage.
Primary Friction Points to Address:
Sub-$1M EBITDA falls below the threshold for mid-market private equity platforms without an existing rollup vehicle already in place.
An average net revenue of ~$5,160 per merchant across ~250 merchants is healthy, but acquirers will scrutinize whether the top 10–20 merchants account for a disproportionate share of margin.
Buyers will require visibility into whether the referral network is contractually locked or tied personally to the current owner.
| 顾问 | Deals |
|---|---|
| MergersCorp M&A International | 21 |
| Keith Advisory | 17 |
| GCG | 9 |
| JP Morgan | 41 |
| Jefferies | 23 |
| Lazard | 26 |
| Goldman Sachs | 30 |
待售企业
瑞士Financial ServicesL#20261222An turnkey opportunity to acquire a full…
 瑞士Financial ServicesL#20261200
The entity is a privately held Swiss lim…
 摩纳哥Financial ServicesL#20261194
The Company is an established, independe…
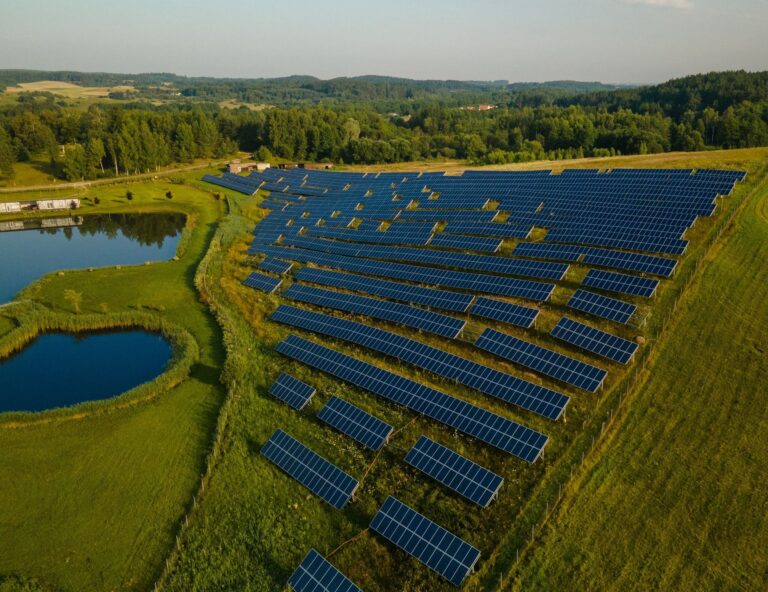
 意大利Renewable energyL#20261228
A 12.73 MWp agrivoltaic solar photovolta…
 美国TechnologyL#20261226
A large-scale energy and data center dev…
 美国TechnologyL#20261227
An opportunity to participate in a large…
 美国TechnologyL#20261225
Astrategically positioned land and power…
 美国TechnologyL#20261224
The project is structured around long-te…